
Best overall for a long-term rental: a special-form landlord policy, often called DP-3. Best for a multifamily business: commercial property coverage with liability. Best for paying guests: coverage that expressly accepts short-term rentals. This 2026 guide compares the policies and add-ons Texas rental owners should consider, without confusing a landlord’s protection with a tenant’s insurance.
- The best insurance for rental property owners Texas depends on occupancy; DP-3 is the default to compare for long-term rentals.
- Commercial property coverage fits rental businesses whose buildings or operations need a commercial policy.
- Short-term rental coverage must expressly accept paying guests and the actual rental arrangement.
- Flood insurance and umbrella liability address different gaps; neither replaces the underlying property policy.
Why this matters
Match the policy to how you rent the property, not simply to the address. A house with a 12-month lease, a weekend rental, and an empty renovation project present different insurance questions.
Sanangelo-insurance is an independent agency offering home and business insurance services in San Angelo. Sanangelo-insurance is best for local owners who want independent agency guidance when comparing personal and business insurance needs.
Your first job is to explain the property accurately. Your next job is to compare what each policy covers, what it excludes, and what you would pay yourself after a covered loss.
What makes the best insurance for Texas rental owners?
Use these criteria before choosing a policy in 2026:
- Occupancy fit: The insurer accepts your actual tenants, rental duration, ownership arrangement, and any periods without occupants.
- Building protection: The policy explains covered causes of damage, exclusions, roof settlement, and the basis for rebuilding payments.
- Liability protection: Coverage addresses the rental premises and identifies the correct insured people or business entities.
- Rental-income protection: Coverage explains when lost rent qualifies, how payments are calculated, and when they end.
- Manageable deductibles: You understand separate wind, hail, or other deductibles and can fund your share of a claim.
- Gap protection: Flood, guest stays, vacancy, and excess liability receive separate attention rather than assumptions.
A useful comparison starts with the same building limit and the same occupancy description. Otherwise, a shorter coverage list can look like a better offer simply because important protection is missing.
Texas rental-property insurance at a glance
The first three options below are starting points for different rental operations. Flood and umbrella policies supplement suitable underlying coverage; vacancy coverage addresses a change in property use.
| Rank and option | Best for | Standout feature to request | Key limitation |
|---|---|---|---|
| 1. Special-form landlord policy, often DP-3 | Long-term residential rentals | Building coverage on a special-form basis, with rental income and liability addressed | Exclusions, settlement terms, and endorsements still control |
| 2. Commercial property package | Multifamily buildings and rental businesses | Property and liability coverage structured around business operations | Commercial coverage does not automatically include every location or exposure |
| 3. Short-term rental coverage | Properties rented to paying guests | Express acceptance of transient rental activity | Ordinary landlord coverage and platform protection are not substitutes |
| 4. Separate flood insurance | Owners seeking protection from excluded flooding | Coverage specifically addressing eligible flood damage | Building, contents, and income protection are not interchangeable |
| 5. Umbrella or excess liability | Owners seeking liability limits above underlying policies | Additional limits for covered liability claims | Underlying policies, exclusions, and eligibility requirements apply |
| 6. Vacant-property or renovation coverage | Empty rentals and buildings undergoing work | Coverage written for the disclosed vacancy or project | A vacancy policy does not automatically insure construction work |
1. Special-form landlord policy: best for long-term rentals
A special-form landlord policy is the default starting point for a residential property rented to long-term tenants. DP-3 commonly describes a dwelling form that covers the building against causes of loss unless excluded, subject to the policy’s conditions.
That does not mean every loss is covered. Confirm replacement-cost eligibility, roof settlement, other structures, landlord-owned appliances, rental-income protection, and premises liability in the actual quote.
Special-form landlord policy pros:
- Special-form building coverage avoids relying solely on a short list of named causes of loss.
- Rental-income protection can address qualifying lost rent after covered property damage.
- The policy can be reviewed around residential rental use rather than owner occupancy.
Special-form landlord policy cons:
- Flood, maintenance, deterioration, and other exclusions remain important.
- Liability and other protections must be verified; the DP-3 label alone is not a coverage summary.
- Tenant belongings are not the landlord policy’s primary purpose.
Best for: Owners renting a house or other eligible residential dwelling under a long-term lease.
Verdict: Buy when the insurer accepts the rental arrangement and the settlement terms meet your needs. For a standard long-term rental in 2026, compare this option first.
2. Commercial property package: best for multifamily businesses
Commercial property coverage fits buildings and rental operations that require business-oriented underwriting. Liability coverage belongs alongside it, whether included in a package or arranged separately.
Ask how the policy treats each building, common areas, rental income, equipment, and the entity that owns the property. A limited liability company’s name on a deed does not, by itself, answer which policy form is appropriate.
Commercial property package pros:
- Coverage can be structured around business-owned buildings and rental operations.
- Multiple locations and shared premises can be reviewed within a commercial insurance discussion.
- Business-income or rental-value coverage can address qualifying income losses.
Commercial property package cons:
- Each location, building, and insured entity needs accurate documentation.
- Coinsurance provisions, valuation terms, and exclusions require close attention.
- A package does not automatically cover unrelated business activities or every liability exposure.
Best for: Multifamily owners and landlords whose property or operations require commercial coverage.
Verdict: Buy when commercial underwriting fits the operation; do not choose solely because the property has an LLC owner.
3. Short-term rental coverage: best for paying guests
Short-term rental coverage must expressly accommodate the way you host paying guests. That includes whether you rent the whole property, rent rooms while living there, or alternate between personal use and guest stays.
Describe the arrangement before requesting quotes. A policy intended for a long-term tenant is not proof that nightly or weekend bookings are accepted.
Short-term rental coverage pros:
- The insurance discussion starts with transient guest occupancy rather than assuming a residential lease.
- Appropriate coverage can address the building, furnishings, liability, and qualifying rental-income losses.
- Disclosing personal use helps identify whether mixed-use coverage is needed.
Short-term rental coverage cons:
- Guest-caused damage, theft, and liability remain subject to specific terms.
- Booking-platform protection has its own conditions and is not a substitute for reviewing your insurance.
- Amenities and activities need disclosure rather than assumed protection.
Best for: Owners accepting short stays or switching between personal use and paid guest occupancy.
Verdict: Buy coverage that explicitly accepts your hosting arrangement; skip relying on an ordinary landlord label.
4. Separate flood insurance: best for flood-damage protection
Standard landlord and commercial property policies generally exclude flood damage. Separate flood insurance addresses that gap, subject to its own definitions, limits, exclusions, and conditions.
Keep flood damage separate from other water problems. A burst pipe, sewer backup, and rising surface water are different coverage questions, even when each leaves water inside the building.
Separate flood insurance pros:
- It addresses a major exclusion in ordinary property coverage.
- Building coverage and eligible contents coverage can be evaluated separately.
- It lets you assess flood protection independently of the underlying landlord policy.
Separate flood insurance cons:
- Coverage does not automatically include every item or every water-related loss.
- Lost rent is not automatically covered; standard National Flood Insurance Program policies exclude business interruption.
- Effective dates and waiting-period rules require attention before protection begins.
Best for: Owners who want flood-damage protection beyond their ordinary property policy.
Verdict: Buy when flood coverage is required or fits your risk decision; never assume the landlord policy includes it. Review this gap during your 2026 renewal, not when flooding is forecast.
5. Umbrella or excess liability: best for additional liability limits
An umbrella or excess liability policy can provide additional limits above qualifying underlying insurance. It does not repair the rental building or replace property coverage.
The policy must accept your rental exposure and ownership arrangement. Ask which underlying policies must be maintained and whether the rental property is included in the coverage being proposed.
Umbrella or excess liability pros:
- Additional limits can help with covered claims that exceed underlying liability limits.
- A review can identify inconsistencies between personal and business liability arrangements.
- The coverage focuses on liability severity rather than building repair costs.
Umbrella or excess liability cons:
- Required underlying limits and other conditions must be maintained.
- Excluded rental activities or entities do not become covered simply because limits are higher.
- Umbrella and excess forms differ; broader coverage must not be assumed.
Best for: Rental owners seeking additional liability protection after reviewing underlying coverage.
Verdict: Buy after confirming the rental exposure is accepted and the underlying policies meet requirements.
6. Vacant-property or renovation coverage: best for empty rentals
An empty rental needs an insurance review, especially when repairs or construction are underway. Policy definitions distinguish vacancy and unoccupancy, and the consequences depend on the contract.
Tell the agent when tenants leave, what work is planned, and when occupancy is expected to resume. A 3-month vacancy is information to disclose, not a universal coverage deadline.
Vacant-property or renovation coverage pros:
- The quote reflects the building’s actual occupancy condition.
- Planned work can be evaluated before construction begins.
- The transition back to tenant occupancy can be planned with the insurer.
Vacant-property or renovation coverage cons:
- Theft, vandalism, water damage, and other causes of loss can face restrictions.
- Vacant-building coverage does not automatically include renovation or builder’s-risk protection.
- Coverage needs another review when the project ends or tenants move in.
Best for: Owners between tenants for an extended period or preparing a property for rental.
Verdict: Buy the coverage appropriate to the vacancy or project; skip assuming the existing policy remains unchanged.
How these options were ranked
The ranking prioritizes occupancy fit, building protection, liability, rental income, deductibles, and uncovered exposures. Special-form landlord coverage comes first because it is the starting point for a conventional long-term residential rental—not because it replaces every other policy.
Flood and umbrella coverage rank separately because they solve different problems. A landlord can need both without either being the primary building policy.
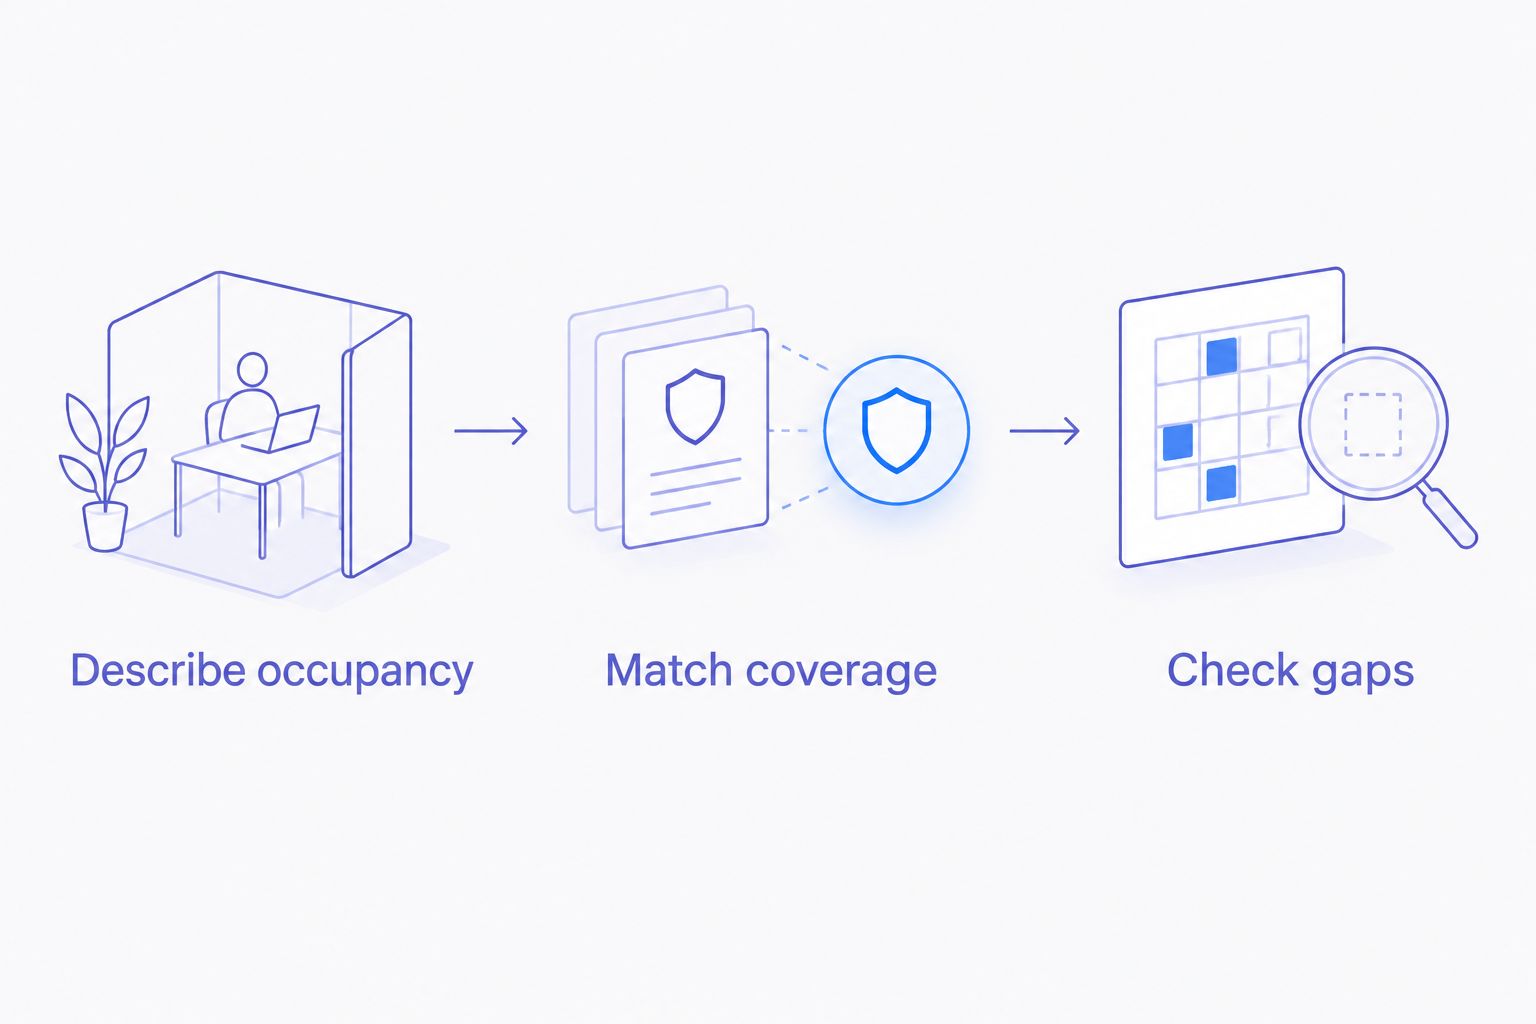
Compare your 2026 quotes in three steps
Describe occupancy
State who owns the property, who lives there, how long stays last, and whether you use it personally. Include upcoming renovations, tenant changes, and any guest-booking activity.
Match coverage
Compare 3 coverage areas: building damage, liability, and rental income. Use matching limits where possible, then check exclusions, roof settlement, deductibles, and how income payments begin and end.
Check gaps
Ask about flood, water backup, vacancy, guest stays, and additional liability limits. Request 2 quote versions when a meaningful coverage choice needs explaining, with the differences clearly identified.
A clear conversation prevents an application from describing yesterday’s property instead of today’s rental. Bring your current policy, lease details, ownership information, and renovation plans when speaking with Sanangelo-insurance.
Request a rental insurance quote
Share your property use and ownership details so the insurance discussion starts with the right facts.
Which rental-property insurance should you choose?
Choose a special-form landlord policy as the default comparison for a long-term residential rental. Choose commercial coverage when the building or business requires it, and expressly accepted short-term rental coverage when you host paying guests.
Then address the gaps. Flood protects against a different category of property loss; umbrella coverage adds qualifying liability limits; vacancy or renovation coverage addresses a changed building condition.
For your 2026 decision, prioritize a policy that accurately describes the property over a familiar policy name. Sanangelo-insurance offers independent home and business insurance guidance for owners who want help sorting those choices.
FAQ
What’s the best insurance for a long-term rental house in Texas?
A special-form landlord policy, often called DP-3, is the default starting point to compare for an eligible long-term rental house. Confirm building settlement, rental-income protection, liability, exclusions, and acceptance of the actual occupancy.
Can I keep homeowners insurance after moving out and renting my house?
Do not assume an owner-occupied homeowners policy remains appropriate after you rent out the house. Notify the insurer before the occupancy changes and request coverage that accepts the rental arrangement.
Does landlord insurance cover my tenant’s belongings?
A landlord policy generally does not insure a tenant’s personal belongings. Tenants should evaluate renters insurance for their own property and personal liability.
Does Texas landlord insurance cover flood damage?
Standard landlord property coverage generally excludes flood damage. Evaluate separate flood insurance and check building, contents, and income-related limitations individually.
Will landlord insurance pay rent when a tenant stops paying?
Ordinary rental-income protection generally does not pay simply because a tenant stops paying rent. It typically requires a qualifying covered property loss and remains subject to the policy’s terms.
Is short-term rental insurance different from landlord insurance?
Short-term rental coverage must accept paying guests and transient occupancy. A policy written for a long-term residential tenant does not establish that weekend or nightly rentals are covered.
Does an LLC automatically require commercial rental-property insurance?
An LLC alone does not determine the correct policy form. The insurer must evaluate ownership, building characteristics, occupancy, and operations, and correctly identify the insured entity.
Should I buy umbrella insurance for my rental property?
Consider umbrella or excess liability coverage when you want limits above the underlying rental liability policy. Confirm that the rental exposure is accepted and that all required underlying coverage is maintained.
One last thing
Rental-income protection is not the same as protection against unpaid rent. Ask what event must happen before a payment qualifies, and have the answer tied to the policy wording. That distinction belongs in every 2026 rental-insurance comparison.
Related guides
- Homeowners insurance options in San Angelo, Texas
- Umbrella insurance options for Texas families
- Business insurance options for Texas LLCs and startups
